The Federal Government is considering legislation to protect Nigeria’s economic policy framework from abrupt reversals by successive administrations, in a move aimed at promoting policy consistency and strengthening investor confidence.
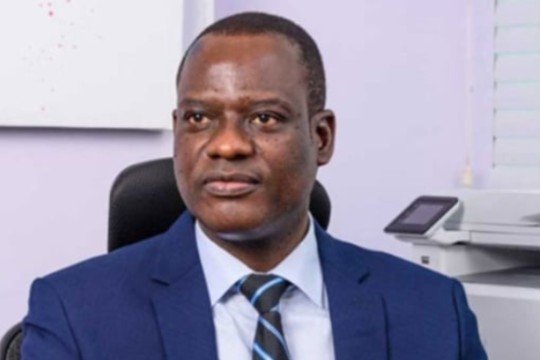
The Minister of Finance and Coordinating Minister of the Economy, Taiwo Oyedele, disclosed this on Monday at the 32nd Nigerian Economic Summit in Abuja, where he presented a proposed Nigeria Economic Policy Framework.
Oyedele said the government was seeking a national consensus on economic principles that could be backed by law to guide future decisions on taxation, tariffs, subsidies, investment and industrial development.
According to him, the proposed framework is intended to ensure that economic policies are sustained across administrations rather than abandoned because of political considerations.
“We now need to lock it in, in institutions, in law, as well as policy framework, so that it can be enduring,” the minister said during a panel session.
He explained that the government was considering whether the framework should be enacted into law as part of efforts to strengthen institutions and prevent future administrations from reversing policies considered necessary for economic stability.
Oyedele specifically criticised the possibility of returning to petrol subsidy payments, arguing that reversing the policy could recreate economic distortions the government had sought to address.
However, the minister clarified that the proposed Nigeria Economic Policy Framework remains a consultation draft and has not yet received approval as government policy.
Public consultation is expected to run until November 27, 2026, after which the document will proceed to the Federal Executive Council for approval and the National Economic Council for endorsement.
The framework also proposes mandatory policy impact assessments before major economic interventions. Under the proposal, policymakers would be required to explain the problems a policy seeks to solve, the evidence supporting it, its expected costs and benefits, and the conditions under which it should end.
The government is also proposing an annual National Economic Scorecard to measure the country’s economic performance using indicators such as real wages, productive employment and poverty levels.
Oyedele said Nigeria’s economic challenges were partly linked to inconsistent policies, inadequate consultation and decisions that undermined business confidence.
He described policy uncertainty as an additional burden on businesses, arguing that frequent changes in government decisions discourage investment and weaken economic growth.
The proposed framework is organised around seven interconnected areas: stability, productivity, enterprise, capital, people, markets and institutions.
On industrial development, the minister said tariffs should help local businesses become competitive rather than provide permanent protection from foreign competition.
He maintained that economic policies should support productivity, encourage investment and improve household incomes, rather than rely solely on headline economic growth figures.
The proposal comes amid the Tinubu administration’s ongoing economic reforms, which include the removal of petrol subsidies and changes to the foreign exchange system.
While the government is seeking to establish a long-term policy framework that successive administrations can follow, the proposed legislation has not been enacted, and its final provisions will depend on the consultation and approval processes.
The government has invited Nigerians, businesses and other stakeholders to contribute to the consultation process before the framework is finalised.
About the Author